Federal Student Loan Repayment 2026: A Comprehensive Guide for Graduates
Understanding the New Federal Student Loan Repayment Options: A 2026 Overview for U.S. Graduates
For millions of U.S. graduates, student loans represent both an investment in their future and a significant financial obligation. As we approach 2026, the landscape of federal student loan repayment is evolving, bringing with it new opportunities and complexities. Navigating these changes effectively is crucial for managing your debt, avoiding default, and ultimately achieving financial well-being. This comprehensive guide will break down the key federal student loan repayment options available in 2026, focusing on what graduates need to know to make informed decisions about their financial future.
The federal government continuously refines its student loan programs to address economic shifts and borrower needs. The year 2026 is poised to be a pivotal time, with the full implementation of recent reforms and the potential for further adjustments. Understanding these options, from the traditional standard plans to the increasingly popular income-driven repayment (IDR) plans, is not just about knowing the rules; it’s about strategizing for your specific financial situation. Whether you’re a recent graduate or have been managing loans for years, this overview of student loan repayment 2026 will provide clarity and actionable insights.
The Evolving Landscape of Federal Student Loan Repayment
The federal student loan system has undergone significant transformations in recent years. These changes are primarily aimed at making repayment more affordable and flexible, especially for borrowers facing financial hardship. The most notable development has been the introduction and refinement of income-driven repayment plans, which adjust monthly payments based on a borrower’s income and family size. These plans offer a crucial safety net, preventing many from falling into default and providing a pathway to loan forgiveness after a certain period.
As we look towards 2026, the emphasis remains on providing accessible and manageable repayment pathways. Graduates entering the workforce or those already established need to be aware of how these options function and which one best aligns with their career trajectory, income stability, and long-term financial goals. The goal is not just to repay your loans, but to do so in a way that doesn’t compromise your ability to save, invest, or pursue other life milestones.
Key Federal Student Loan Repayment Options for 2026
Let’s delve into the specific repayment plans that will be central to federal student loan repayment 2026. Each plan has distinct features, eligibility requirements, and potential benefits. It’s essential to understand these nuances before making a choice.
1. The Standard Repayment Plan
The Standard Repayment Plan is the default option for most federal student loans. Under this plan, you pay a fixed amount each month for up to 10 years (or up to 30 years for consolidated loans). The payments are calculated to ensure your loan is paid off in full within this timeframe. While it typically results in the lowest total interest paid over the life of the loan, the monthly payments can be higher compared to income-driven plans.
- Key Feature: Fixed monthly payments.
- Duration: Up to 10 years (or 30 for consolidated loans).
- Benefit: Lowest total interest cost.
- Consideration: Potentially higher monthly payments.
2. Graduated Repayment Plan
The Graduated Repayment Plan also has a 10-year term, but unlike the standard plan, your payments start low and gradually increase, usually every two years. This plan is designed for borrowers who expect their income to rise over time. While it offers lower initial payments, you’ll pay more interest over the life of the loan compared to the Standard Plan due to the slower principal reduction at the beginning.
- Key Feature: Payments increase over time.
- Duration: Up to 10 years.
- Benefit: Lower initial monthly payments.
- Consideration: Higher total interest paid than Standard Plan.
3. Extended Repayment Plan
If you have more than $30,000 in federal student loan debt, you might be eligible for the Extended Repayment Plan. This plan allows you to repay your loans over a period of up to 25 years. Payments can be fixed or graduated. The longer repayment period means lower monthly payments, but also significantly more interest paid over the life of the loan.
- Key Feature: Longer repayment term (up to 25 years).
- Eligibility: Over $30,000 in federal student loan debt.
- Benefit: Significantly lower monthly payments.
- Consideration: Much higher total interest cost.
Income-Driven Repayment (IDR) Plans: A Deeper Dive for 2026
Income-Driven Repayment (IDR) plans are a cornerstone of federal student loan relief, designed to make monthly payments affordable based on your income and family size. After a certain number of years (typically 20 or 25, or 10 for Public Service Loan Forgiveness), any remaining balance on your loans may be forgiven. For student loan repayment 2026, these plans, particularly the new SAVE plan, are critical.
4. The SAVE Plan (Saving on a Valuable Education) – The Game Changer for 2026
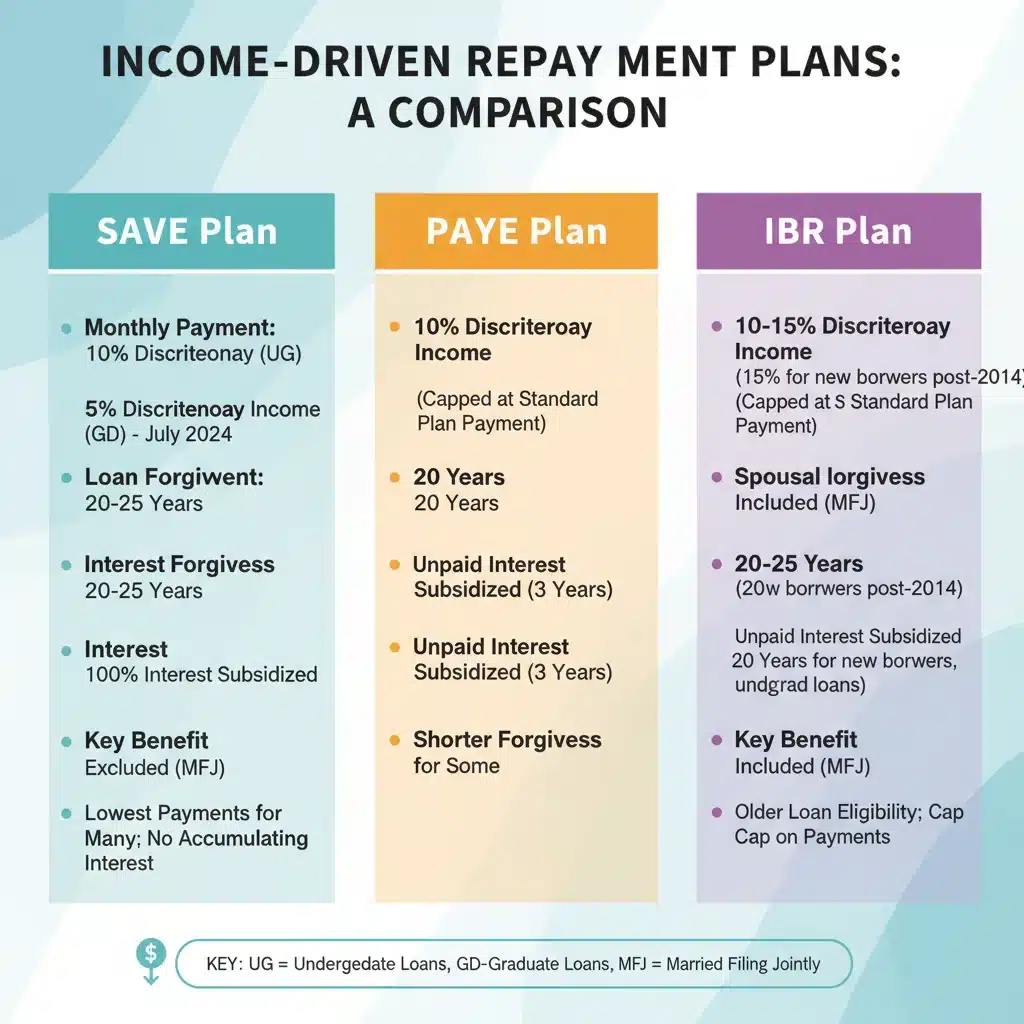
The SAVE Plan, which fully rolled out in 2024, is arguably the most significant improvement to income-driven repayment. It replaces the Revised Pay As You Earn (REPAYE) Plan and offers substantial benefits, particularly for low- and middle-income borrowers. Understanding the SAVE plan is paramount for anyone navigating student loan repayment 2026.
- Lower Payments: Monthly payments are calculated based on a higher percentage of your discretionary income. For undergraduate loans, payments are just 5% of discretionary income (down from 10-15% on other IDR plans). For graduate loans, it’s 10%. If you have both, it’s a weighted average.
- Increased Income Exemption: The amount of income protected from payment calculations is increased from 150% to 225% of the federal poverty line. This means more of your income is considered non-discretionary, leading to lower or even $0 monthly payments for many.
- Interest Subsidy: Perhaps the most impactful feature: if your calculated monthly payment doesn’t cover the monthly interest, the government covers the unpaid interest. This prevents your loan balance from growing due to accruing interest, a common issue with other IDR plans.
- Shorter Forgiveness Timeline for Smaller Balances: Forgiveness can occur as early as 10 years for original principal balances of $12,000 or less. For every additional $1,000 borrowed above $12,000, an additional year of payments is added, up to the standard 20 or 25 years.
- Spousal Income Exclusion: If you’re married and file separately, your spouse’s income is NOT included in the payment calculation, offering significant relief for some couples.
The SAVE Plan is designed to be the most affordable IDR plan for the majority of borrowers. Its interest subsidy feature is revolutionary, addressing a long-standing pain point where balances would grow even with on-time payments under other IDR plans. Graduates should seriously consider the SAVE plan as their primary IDR option for student loan repayment 2026.
5. Pay As You Earn (PAYE) Repayment Plan
The PAYE Plan generally sets your monthly payment at 10% of your discretionary income, but never more than what you would pay under the Standard Repayment Plan. This ‘cap’ is a key differentiator from REPAYE (now effectively replaced by SAVE for new enrollees). Loan forgiveness is available after 20 years of qualifying payments. Eligibility for PAYE requires you to be a new borrower on or after October 1, 2007, and have received a disbursement of a Direct Loan on or after October 1, 2011.
- Key Feature: 10% of discretionary income, capped at Standard Plan payment.
- Duration: 20 years for forgiveness.
- Eligibility: Specific borrower dates.
- Consideration: May be less beneficial than SAVE for many due to higher payment percentage and no interest subsidy.
6. Income-Based Repayment (IBR) Plan
The IBR Plan offers two versions, depending on when you took out your loans. For new borrowers on or after July 1, 2014, payments are 10% of discretionary income. For those who borrowed before July 1, 2014, payments are 15% of discretionary income. In both cases, payments are capped at the Standard Repayment Plan amount. Loan forgiveness is available after 20 or 25 years, respectively. Like PAYE, IBR does not offer the same robust interest subsidy as SAVE.
- Key Feature: 10% or 15% of discretionary income, capped at Standard Plan payment.
- Duration: 20 or 25 years for forgiveness.
- Consideration: Generally less generous than SAVE.
7. Income-Contingent Repayment (ICR) Plan
The ICR Plan is the oldest IDR plan and generally offers the highest monthly payments among the IDR options. Your payment is the lesser of 20% of your discretionary income or what you would pay on a fixed 12-year payment plan, adjusted by income. Forgiveness is available after 25 years. ICR is often used for Parent PLUS loans that have been consolidated into a Direct Consolidation Loan, as it’s the only IDR option available for them.
- Key Feature: 20% of discretionary income or 12-year fixed payment, whichever is less.
- Duration: 25 years for forgiveness.
- Consideration: Generally higher payments; often the only IDR option for consolidated Parent PLUS loans.
Public Service Loan Forgiveness (PSLF) and IDR Plans
For graduates working in public service (government organizations at any level, or eligible non-profit organizations), the Public Service Loan Forgiveness (PSLF) program offers a powerful path to debt relief. Under PSLF, remaining loan balances are forgiven after 120 qualifying monthly payments (10 years) made while working full-time for a qualifying employer. Crucially, these payments must be made under an income-driven repayment plan.
The SAVE Plan is particularly beneficial for PSLF-eligible borrowers because its lower monthly payments mean you pay less out-of-pocket over the 10 years while still qualifying for forgiveness. This makes the combination of SAVE and PSLF an incredibly attractive option for public servants managing their student loan repayment 2026.
Consolidation: Streamlining Your Loans for 2026
Federal student loan consolidation allows you to combine multiple federal student loans into a single Direct Consolidation Loan. This can simplify repayment by giving you one monthly payment and one loan servicer. While it doesn’t necessarily lower your interest rate (it’s a weighted average of your existing rates, rounded up to the nearest one-eighth of a percentage), it can open doors to certain repayment plans or forgiveness programs you might not otherwise qualify for.
For instance, some older federal loans (like FFEL Program loans) may not be directly eligible for all IDR plans or PSLF. Consolidating them into a Direct Consolidation Loan makes them eligible. If you’re considering consolidation for student loan repayment 2026, carefully weigh the pros and cons, including the potential loss of borrower benefits tied to individual loans.
Choosing the Right Repayment Plan for You
Selecting the best repayment plan for your federal student loans is a highly personal decision. There’s no one-size-fits-all answer. Here’s a framework to help you decide for student loan repayment 2026:
1. Assess Your Financial Situation
- Current Income & Expenses: What can you realistically afford each month without compromising other essential expenses or savings goals?
- Future Income Potential: Do you anticipate your income to grow significantly in the coming years? This might make graduated plans or even the Standard Plan more feasible later on.
- Emergency Savings: Do you have a healthy emergency fund? If not, lower monthly payments from an IDR plan might free up cash to build one.
2. Understand Your Loan Types and Balances
- Federal vs. Private: This guide focuses on federal loans. Private loans have different rules.
- Loan Servicer: Know who your loan servicer is. They are your primary point of contact.
- Total Debt: A higher total debt might make extended or IDR plans more appealing for lower monthly payments.
3. Consider Your Career Path and Goals
- Public Service: If you work in public service, PSLF combined with the SAVE plan is likely your best option.
- High-Income Earner: If you expect to earn a high income quickly, the Standard Plan might be best to minimize total interest.
- Uncertain Income/Financial Hardship: IDR plans, especially SAVE, offer crucial flexibility and a safety net.
4. Use the Loan Simulator
The Federal Student Aid (FSA) website offers a Loan Simulator. This invaluable tool allows you to input your specific loan details, income, and family size to compare different repayment plans side-by-side. It can project your monthly payments, total interest paid, and potential forgiveness amounts under each plan. This is a must-use resource for any graduate exploring their student loan repayment 2026 options.
Key Actions for Graduates in 2026
To effectively manage your federal student loans in 2026, consider these essential actions:
1. Know Your Loan Servicer
Your loan servicer is the company that handles your billing and other services. Log in to StudentAid.gov to find out who your servicer is and keep your contact information updated with them.
2. Understand Your Current Repayment Plan
Don’t assume you’re on the best plan. Review your current repayment plan and compare it with the new options available, especially the SAVE Plan. You can change your repayment plan at any time.
3. Apply for an Income-Driven Repayment Plan (if applicable)
If you’re struggling to make payments, or if you want to pursue PSLF, applying for an IDR plan (likely SAVE) is critical. You’ll need to submit income and family size documentation annually to keep your payments adjusted.
4. Re-certify Your Income Annually
If you’re on an IDR plan, you must re-certify your income and family size each year. Missing this deadline can lead to higher payments and capitalized interest. Your servicer will remind you, but it’s ultimately your responsibility.
5. Explore Public Service Loan Forgiveness (PSLF)
If you work for a qualifying employer, ensure you’re tracking your payments and employment carefully. Submit the PSLF Employment Certification Form regularly to confirm your eligibility and track your qualifying payments.
6. Beware of Scams
Be vigilant against student loan scams. No legitimate government agency or loan servicer will ever ask you to pay a fee for student loan help or promise instant forgiveness. Always go directly to StudentAid.gov or your official loan servicer for information.
What if I’m Struggling to Make Payments?
Even with flexible repayment options, some graduates may find themselves in a difficult financial spot. If you’re struggling with your student loan repayment 2026, do not ignore the problem. Contact your loan servicer immediately. They can discuss options such as:
- Changing Repayment Plans: As discussed, switching to an IDR plan like SAVE can significantly lower your monthly burden.
- Deferment: Allows you to temporarily postpone payments. Interest may or may not accrue depending on the type of loan and deferment.
- Forbearance: Also allows you to temporarily stop or reduce payments. Interest typically accrues on all loan types during forbearance.
Both deferment and forbearance should be considered short-term solutions, as interest can accrue and add to your total debt. The goal should be to find a sustainable repayment plan, ideally an IDR plan, that fits your budget.
The Broader Impact of Student Loan Debt
Beyond individual financial planning, the federal student loan system has a profound impact on the broader U.S. economy and society. The changes implemented for student loan repayment 2026 aim to alleviate some of the pressure on graduates, which in turn can stimulate economic activity. When graduates are less burdened by debt, they are more likely to buy homes, start businesses, and contribute to the economy in other meaningful ways.
However, the conversation around student debt is ongoing, with debates about tuition costs, the value of higher education, and the long-term sustainability of the loan system. As a graduate, being informed about these broader discussions can help you advocate for policies that further improve financial accessibility and affordability in education.
Conclusion
Navigating federal student loan repayment can feel overwhelming, but with the right information and a proactive approach, U.S. graduates can confidently manage their debt. The year 2026 brings with it a refined set of options, with the SAVE plan standing out as a particularly beneficial program for many. By understanding the Standard, Graduated, Extended, and various Income-Driven Repayment plans, and utilizing resources like the FSA Loan Simulator, you can make an informed decision that aligns with your financial reality and future aspirations.
Remember to stay in close communication with your loan servicer, regularly review your repayment options, and re-certify your income for IDR plans. Your diligence in managing your federal student loans will pay off, literally, by helping you achieve financial freedom sooner and with less stress. Take control of your student loan repayment 2026 journey, and build a solid financial foundation for your future.
