Student Loan Forgiveness 2026: Eligibility, Deadlines, & Federal Programs
Anúncios
For millions of Americans, student loan debt represents a significant financial burden that can impact life choices, career paths, and overall financial well-being. As we look towards 2026, understanding the landscape of student loan forgiveness 2026 programs is more critical than ever. The federal government continually refines and introduces initiatives designed to provide relief, but navigating these options can be complex. This comprehensive guide aims to demystify the various federal student loan forgiveness programs, outline eligibility requirements, highlight application processes, and pinpoint crucial deadlines for 2026, ensuring you have the most up-to-date information to pursue potential debt relief.
The journey through higher education often comes with the necessity of borrowing money. While student loans enable access to invaluable educational opportunities, the repayment process can be daunting. Thankfully, various avenues for relief exist, primarily through federal programs. These programs are not one-size-fits-all; they cater to different career paths, financial situations, and historical loan contexts. Being well-informed about the specific criteria for each program is the first step toward successfully applying for and receiving student loan forgiveness 2026.
Anúncios
This article will delve into the intricacies of Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) plans, Teacher Loan Forgiveness, and other specialized programs. We will also address common questions, debunk myths, and provide actionable advice to help you prepare your applications and manage your student loan debt effectively. Whether you’re just starting your repayment journey or have been paying for years, understanding your options for student loan forgiveness 2026 could significantly impact your financial future.
Anúncios
Understanding the Landscape of Student Loan Forgiveness 2026
The concept of student loan forgiveness is often misunderstood, leading to confusion and missed opportunities. It’s essential to distinguish between widespread loan cancellation, which typically requires legislative action or executive order, and targeted forgiveness programs, which are already established and available to eligible borrowers. For 2026, the focus remains primarily on these existing federal programs that offer forgiveness under specific conditions.
These programs are designed to assist borrowers who dedicate their careers to public service, struggle with high debt-to-income ratios, or meet other specific criteria. The key to accessing these benefits lies in understanding the nuances of each program and meticulously adhering to their requirements. Keeping an eye on official announcements from the Department of Education is also crucial, as policies and program details can be updated.
The conversation around student loan forgiveness 2026 is dynamic. While major, broad-based forgiveness initiatives often grab headlines, the steady, reliable pathways to relief through established federal programs continue to be the most accessible and predictable for many borrowers. Our goal here is to provide a clear, actionable guide to these pathways.
Public Service Loan Forgiveness (PSLF): Your Path to Debt-Free Public Service
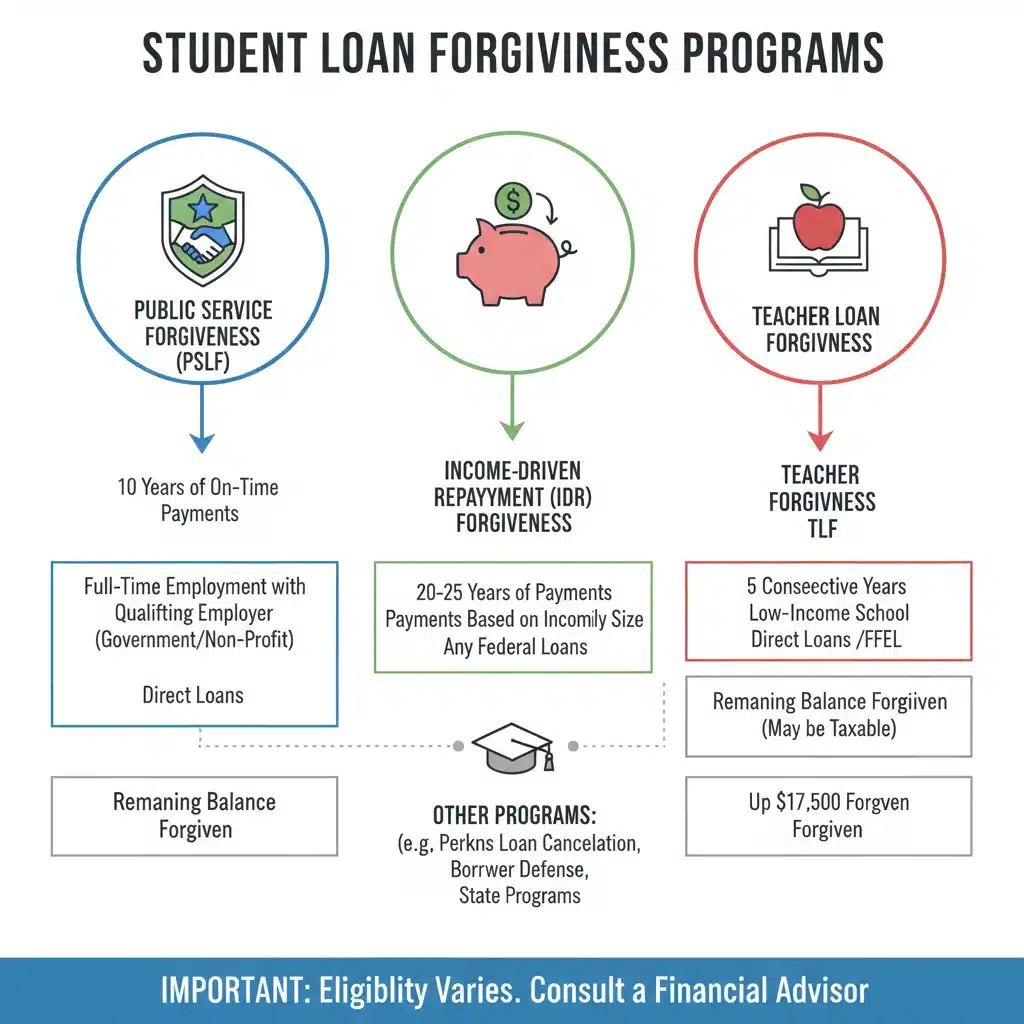
The Public Service Loan Forgiveness (PSLF) program is arguably one of the most impactful options for those working in qualifying non-profit or government organizations. PSLF offers complete forgiveness of the remaining balance on Direct Loans after 120 qualifying monthly payments have been made under a qualifying repayment plan while working full-time for a qualifying employer. For borrowers aiming for student loan forgiveness 2026 through PSLF, understanding these core components is paramount.
Eligibility for PSLF
- Eligible Loans: Only Direct Loans qualify. If you have FFEL Program loans or Perkins Loans, you’ll need to consolidate them into a Direct Consolidation Loan to be eligible.
- Qualifying Employment: You must be employed full-time by a U.S. federal, state, local, or tribal government organization (including military service) or a not-for-profit organization that is tax-exempt under Section 501(c)(3) of the Internal Revenue Code.
- Qualifying Payments: You must make 120 separate monthly payments. These payments must be made in full, on time (within 15 days of the due date), and while you are employed full-time by a qualifying employer.
- Qualifying Repayment Plan: Payments must be made under an income-driven repayment (IDR) plan. Other plans like the Standard Repayment Plan can count, but only if you end up paying off your loan before reaching 120 payments.
The PSLF Application Process and Deadlines for 2026
There isn’t a single “application deadline” for PSLF in the traditional sense, as it’s an ongoing program. However, it’s crucial to submit the PSLF Employer Certification Form (ECF) annually or whenever you change employers. This form helps track your progress and ensures your employment and payments are being correctly counted. For those anticipating reaching 120 payments by or during 2026, ensure all your ECFs are up to date. Once you’ve made 120 qualifying payments, you’ll submit a PSLF application to receive forgiveness.
It’s highly recommended to use the PSLF Help Tool on the Federal Student Aid website. This tool helps you find out if your employer qualifies, guide you through the ECF process, and track your progress. Regular submission of the ECF is vital to avoid surprises when you finally apply for forgiveness. Don’t wait until you think you’ve made all 120 payments to submit your first form; do it early and often.
Income-Driven Repayment (IDR) Plans: A Safety Net for Borrowers
Income-Driven Repayment (IDR) plans are designed to make student loan payments more manageable by capping them at an affordable percentage of your discretionary income. While IDR plans primarily focus on affordability, they also offer a path to forgiveness after 20 or 25 years of qualifying payments (depending on the plan and whether you have graduate or undergraduate loans). For many, these plans are the primary route to student loan forgiveness 2026 if PSLF isn’t an option.
Types of IDR Plans:
- Revised Pay As You Earn (REPAYE) Plan: Generally 10% of discretionary income.
- Pay As You Earn (PAYE) Plan: Generally 10% of discretionary income, but never more than the 10-year Standard Repayment Plan amount.
- Income-Based Repayment (IBR) Plan: Generally 10% or 15% of discretionary income, depending on when you received your first loans.
- Income-Contingent Repayment (ICR) Plan: The lesser of 20% of discretionary income or what you’d pay on a fixed 12-year payment plan, adjusted by income.
- Saving on a Valuable Education (SAVE) Plan: This is the newest IDR plan, replacing REPAYE. It offers significant benefits, including lower monthly payments for many, and can lead to forgiveness in as little as 10 years for those with low original loan balances.
IDR Forgiveness and Application for 2026
Under IDR plans, any remaining loan balance is forgiven after 20 or 25 years of payments (or as little as 10 years for certain SAVE Plan borrowers). The key is to enroll in an IDR plan and recertify your income and family size annually. Failure to recertify can lead to your payments reverting to the standard amount, and any interest not covered by your payment may be capitalized, increasing your loan balance.
There are no specific application deadlines for IDR forgiveness in 2026; rather, forgiveness occurs automatically once you meet the payment threshold. However, you must proactively apply for an IDR plan and recertify your information each year. The annual recertification deadline is typically one year from your last application or recertification date. Missing this can delay your progress towards student loan forgiveness 2026 or beyond.
Teacher Loan Forgiveness Program: Supporting Educators
The Teacher Loan Forgiveness Program is designed to encourage individuals to enter and remain in the teaching profession in low-income schools. Eligible teachers can receive up to $17,500 in loan forgiveness on their Direct Subsidized and Unsubsidized Loans and their Subsidized and Unsubsidized Federal Stafford Loans.
Eligibility for Teacher Loan Forgiveness
- Qualifying Employment: You must teach full-time for five complete and consecutive academic years in a low-income elementary school, secondary school, or educational service agency.
- Loan Types: Forgiveness applies to Direct Subsidized and Unsubsidized Loans, and Subsidized and Unsubsidized Federal Stafford Loans.
- Loan Disbursement: The loans for which you are seeking forgiveness must have been made before the end of your five academic years of qualifying teaching service.
Application Process and Deadlines for 2026
After completing your five required years of teaching service, you can apply for forgiveness by submitting the Teacher Loan Forgiveness Application to your loan servicer. There isn’t a specific deadline for applying in 2026, but it’s best to apply as soon as you meet the eligibility criteria. Keep meticulous records of your employment, including letters from your school and district, to support your application. This program can be an excellent stepping stone for educators looking for student loan forgiveness 2026.
Other Specialized Forgiveness Programs and Discharges
Beyond the major programs, several other avenues exist for student loan relief, each with specific criteria:
- Total and Permanent Disability (TPD) Discharge: If you become totally and permanently disabled, you may be eligible to have your federal student loans discharged. This typically requires documentation from a physician, the Social Security Administration, or the Department of Veterans Affairs.
- Borrower Defense to Repayment: This program provides loan forgiveness if your school misled you or engaged in other misconduct in violation of certain state laws. The application process involves submitting a claim to the Department of Education.
- Closed School Discharge: If your school closes while you’re enrolled or soon after you withdraw, you might be eligible for a discharge of your federal student loans, provided you didn’t complete your program or transfer your credits to another school.
- Perkins Loan Cancellation: Perkins Loans have their own cancellation provisions for certain professions, including teachers, nurses, law enforcement officers, and child and family service agency employees. The percentage of the loan cancelled increases over time.
Each of these programs has unique application processes and required documentation. If you believe you might qualify for any of these, it’s crucial to contact your loan servicer or the Department of Education for detailed instructions and to understand any specific deadlines that might apply to your situation for student loan forgiveness 2026.
Key Steps to Prepare for Student Loan Forgiveness 2026
Proactive preparation is essential for maximizing your chances of receiving student loan forgiveness. Here are actionable steps you should take:
1. Understand Your Loan Types
The first and most critical step is to know what type of federal student loans you have. Only certain loan types are eligible for specific forgiveness programs. You can find this information by logging into StudentAid.gov. If you have FFEL or Perkins Loans, consider consolidation into a Direct Consolidation Loan if you aim for PSLF or certain IDR benefits.
2. Track Your Payments and Employment
Meticulously track your payments and employment history, especially if you are pursuing PSLF or Teacher Loan Forgiveness. Keep records of pay stubs, employment contracts, and any correspondence with your loan servicer. For PSLF, submitting the Employer Certification Form regularly is non-negotiable.
3. Enroll in the Correct Repayment Plan
Ensure you are enrolled in a qualifying repayment plan, especially for PSLF (an IDR plan is usually required) or if you are working towards IDR forgiveness. If your financial situation changes, update your IDR plan immediately.
4. Stay Informed About Policy Changes
Federal student loan policies can change. Regularly check the Department of Education’s Federal Student Aid website for updates, announcements, and any new initiatives that might impact student loan forgiveness 2026. Subscribe to official newsletters if available.
5. Consolidate When Necessary
If you have older FFEL Program loans or Perkins Loans, consolidating them into a Direct Consolidation Loan can make them eligible for PSLF and certain IDR plans. However, consolidation resets your payment count for forgiveness programs, so weigh the pros and cons carefully or consult with a financial aid advisor.
6. Beware of Scams
Unfortunately, student loan forgiveness scams are prevalent. Be wary of any company that charges a fee for services you can get for free from your loan servicer or the Department of Education. Never share your FSA ID or bank account information with unverified third parties.
Common Questions About Student Loan Forgiveness 2026
Will there be widespread student loan forgiveness in 2026?
While the political landscape can shift, as of now, there are no specific plans for widespread, across-the-board student loan forgiveness in 2026 outside of existing targeted programs. Borrowers should focus on qualifying for established federal programs rather than waiting for broad cancellation.
What happens if I don’t qualify for any forgiveness programs?
If you don’t qualify for forgiveness, focus on managing your loans effectively. Explore income-driven repayment plans to make payments affordable, consider deferment or forbearance in times of financial hardship, and look into refinancing options for private loans (though refinancing federal loans means losing federal protections).
Do I have to pay taxes on forgiven student loan debt?
Generally, student loan debt forgiven under PSLF is not considered taxable income by the IRS. However, forgiveness received through IDR plans typically is considered taxable income. There have been temporary provisions (like those under the American Rescue Plan Act) that made IDR forgiveness tax-free through 2025. It’s crucial to consult a tax professional regarding your specific situation for student loan forgiveness 2026 as tax laws can change.
Can I get forgiveness for private student loans?
Federal student loan forgiveness programs (like PSLF, IDR forgiveness, Teacher Loan Forgiveness) apply only to federal student loans. Private student loans generally do not offer forgiveness options, though some lenders may have hardship programs or refinancing options. In rare cases, private loans may be discharged in bankruptcy, but this is extremely difficult to achieve.
How often should I check my loan status and forgiveness progress?
It’s advisable to check your loan status and progress towards forgiveness regularly, at least once a year, especially if you are pursuing PSLF. If you’re on an IDR plan, ensure you recertify your income and family size annually to keep your payments correct and your progress on track for student loan forgiveness 2026.
Conclusion: Navigating Your Path to Student Loan Forgiveness 2026
The prospect of student loan forgiveness 2026 offers a beacon of hope for many borrowers burdened by educational debt. While the landscape of student loan relief can seem intricate, understanding the available federal programs—Public Service Loan Forgiveness, Income-Driven Repayment plans, Teacher Loan Forgiveness, and various discharge options—is the key to unlocking potential financial freedom. By diligently checking your eligibility, meticulously tracking your employment and payments, and staying informed about policy updates, you can confidently navigate the path toward reducing or eliminating your student loan debt.
Remember, proactive engagement with your loan servicer and the Federal Student Aid website is paramount. Don’t wait for forgiveness to come to you; actively pursue the programs for which you qualify. The financial relief offered by these programs can be life-changing, enabling you to pursue your career goals, save for the future, and achieve greater financial stability. Start your preparation today to ensure you are well-positioned to benefit from student loan forgiveness 2026 and beyond.
