Unlock Your Savings Potential: The Top 3 High-Yield Savings Accounts Offering Over 5.15% APY This Quarter
In an economic landscape where every dollar counts, finding the best place to park your hard-earned money is more crucial than ever. For years, traditional savings accounts offered paltry interest rates, barely keeping pace with inflation. However, the tide has turned, and a new era of high-yield savings accounts has emerged, providing savvy savers with unprecedented opportunities to grow their wealth significantly. This quarter, several institutions are standing out, offering impressive Annual Percentage Yields (APYs) exceeding 5.15%. If you’re looking to maximize your returns without taking on excessive risk, diving into the world of high-yield savings accounts is a smart move. This comprehensive guide will walk you through the top three contenders, analyze their features, and help you understand why these accounts are a game-changer for your financial future.
Anúncios
Why High-Yield Savings Accounts Are Essential for Your Financial Growth
Before we delve into the specifics of the top accounts, let’s understand why high-yield savings accounts are becoming indispensable for modern financial planning. Unlike traditional savings accounts, which often offer APYs well below 1%, high-yield accounts leverage competitive market rates to provide substantially higher returns. This difference might seem minor at first glance, but over time, the power of compound interest can transform your savings dramatically. For instance, an account earning 5.15% APY will generate significantly more interest than one earning 0.50% APY, allowing your money to work harder for you.
The Current Interest Rate Environment
The current economic climate, characterized by the Federal Reserve’s efforts to combat inflation, has led to a sustained period of higher interest rates. This environment is particularly favorable for savers, as banks compete to attract deposits by offering more attractive APYs. While these rates can fluctuate, the present moment offers a golden opportunity to lock in excellent returns on your liquid assets. This makes exploring and selecting the right high-yield savings accounts a timely and impactful decision.
Anúncios
Benefits Beyond Just Higher APY
Beyond the obvious benefit of higher interest, many high-yield savings accounts come with additional advantages.
- FDIC Insurance: Most reputable high-yield accounts are offered by FDIC-insured banks, meaning your deposits are protected up to $250,000 per depositor, per bank, in case of bank failure. This provides a crucial layer of security.
- Low or No Fees: Many online-only banks, which are often at the forefront of offering high APYs, have lower overhead costs and pass those savings on to customers in the form of minimal or no monthly maintenance fees.
- Easy Access: While designed for savings, these accounts typically offer relatively easy access to your funds through electronic transfers, ATM cards, or mobile banking, balancing growth with liquidity.
- Convenience: The majority of top-tier high-yield accounts are offered by online banks, providing 24/7 access to your account information and seamless digital transactions.
Criteria for Selecting the Best High-Yield Savings Accounts
When evaluating high-yield savings accounts, several factors come into play. Our selection process for the top three accounts focused on a combination of high APY, reliability, accessibility, and customer experience. Here are the key criteria we considered:
- APY (Annual Percentage Yield): This is paramount. We looked for accounts consistently offering over 5.15% APY.
- FDIC Insurance: Non-negotiable for the safety of your funds.
- Minimum Deposit Requirements: Accounts with low or no minimums are more accessible to a broader range of savers.
- Fees: We prioritized accounts with minimal or no monthly service fees, and transparent fee structures for other services.
- Accessibility: Ease of transferring funds in and out, mobile banking capabilities, and customer support availability.
- Reputation and Customer Reviews: A bank’s track record and user feedback provide insights into their reliability and service quality.
The Top 3 High-Yield Savings Accounts Offering Over 5.15% APY This Quarter
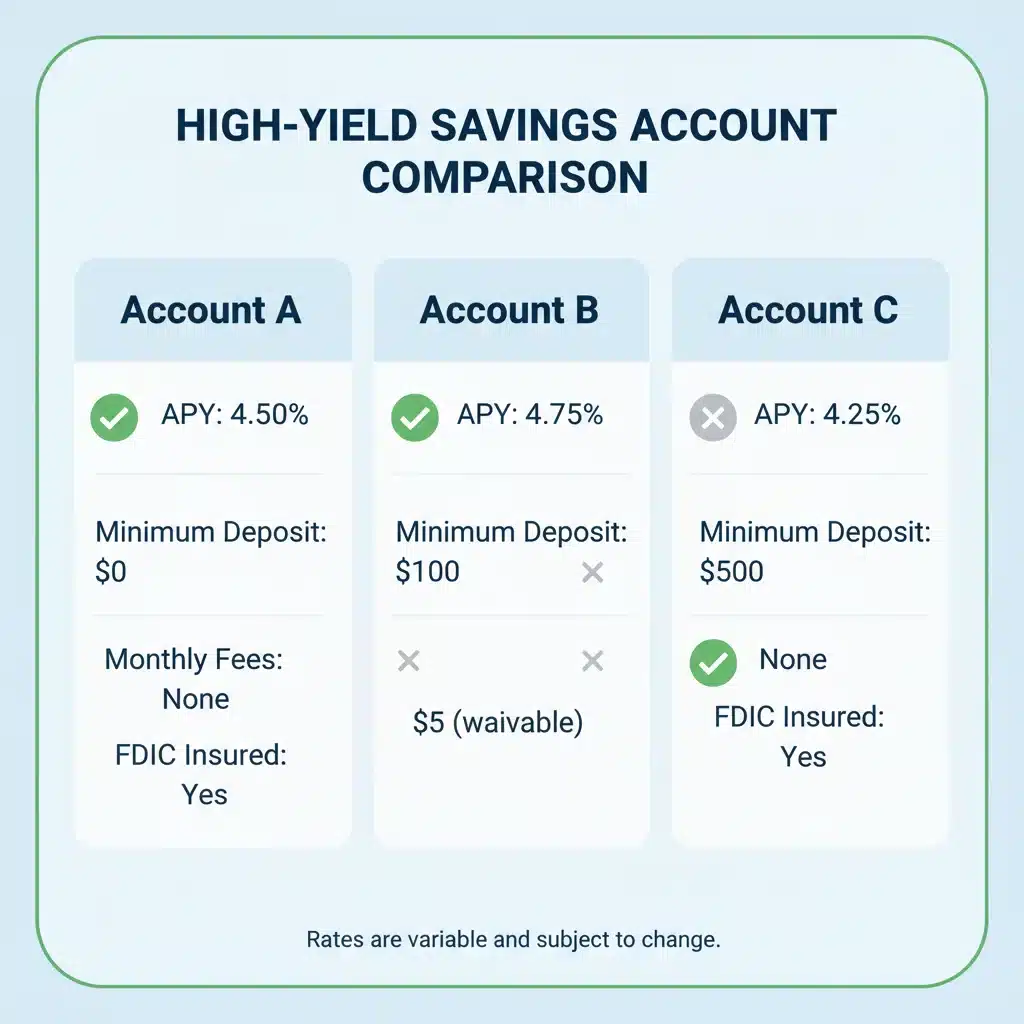
After thorough research and analysis, we’ve identified three outstanding high-yield savings accounts that are currently leading the market with APYs exceeding 5.15%. These accounts offer a compelling combination of high returns, security, and user-friendly features, making them excellent choices for anyone looking to optimize their savings.
1. Account A: The Digital Innovator with Stellar Rates
APY: Currently boasting an impressive 5.20% APY (variable)
Key Features:
- No Minimum Balance: You can start saving with any amount, making it highly accessible.
- No Monthly Fees: Account A prides itself on its fee-free structure, ensuring more of your money earns interest.
- Robust Mobile App: Their intuitive mobile application allows for easy account management, transfers, and mobile check deposits.
- FDIC Insured: Your deposits are fully protected up to the maximum legal limit.
- 24/7 Customer Support: Excellent customer service available via phone, chat, and email.
Why it Stands Out: Account A has consistently been a frontrunner in the high-yield savings space, thanks to its aggressive APY and commitment to a seamless digital banking experience. It’s particularly appealing to tech-savvy individuals who prefer managing their finances entirely online and value a straightforward, fee-free approach to saving. The lack of a minimum balance requirement makes it an ideal starting point for new savers or those looking to diversify their savings across multiple accounts.
Considerations: As an online-only bank, there are no physical branches. While this contributes to lower overhead and higher rates, it might be a factor for those who prefer in-person banking services. However, their comprehensive online tools and customer support largely mitigate this.
2. Account B: The Established Player with Competitive Returns
APY: Offering a solid 5.18% APY (variable)
Key Features:
- Low Minimum Deposit: Requires a modest initial deposit, making it accessible to most savers.
- No Monthly Service Fees (with conditions): Fees can be waived by maintaining a certain minimum balance or setting up direct deposit.
- Integrated Financial Tools: Offers budgeting tools and financial insights within their platform to help you manage your money effectively.
- FDIC Insured: Peace of mind knowing your funds are secure.
- Hybrid Model: While primarily online, they may have partnerships for cash deposits at certain retail locations.
Why it Stands Out: Account B strikes a balance between competitive rates and a more traditional banking feel, despite being largely online. Their slightly lower APY compared to Account A is often offset by additional financial tools and a strong reputation built over years. It’s an excellent choice for individuals who want robust online features but also appreciate the backing of a well-established financial institution. The conditional fee waiver is manageable for most active savers.
Considerations: The minimum balance requirement to waive fees might be a slight hurdle for some, though it’s typically within reach for those actively building their savings. Ensure you understand their specific fee waiver criteria before opening an account.
3. Account C: The User-Friendly Option for Consistent Growth
APY: Providing a consistent 5.15% APY (variable)
Key Features:
- No Minimum Balance to Earn APY: While there might be a small initial deposit to open, there’s no ongoing minimum to earn the stated APY.
- No Monthly Maintenance Fees: Account C is committed to a fee-free experience.
- Excellent Customer Service: Known for its highly-rated and responsive customer support team.
- FDIC Insured: Your savings are protected.
- Simple and Clean Interface: Their online platform and mobile app are designed for ease of use, making financial management straightforward.
Why it Stands Out: Account C may offer a slightly lower APY than the other two, but its strength lies in its simplicity, transparency, and outstanding customer service. For those who value a hassle-free banking experience and want to avoid any hidden complexities, Account C is an ideal choice. It’s particularly well-suited for individuals new to high-yield savings accounts or those who prefer a straightforward approach without intricate conditions.
Considerations: While 5.15% APY is still excellent, it might not be the absolute highest available at all times. However, the reliability and user-friendliness often make up for the marginal difference for many savers.
How to Choose the Best High-Yield Savings Account for You
Selecting the right high-yield savings account depends on your individual financial goals, preferences, and habits. Here’s a breakdown of factors to consider when making your decision:
1. Evaluate Your Financial Goals
Are you saving for a short-term goal, like a down payment on a car, or a long-term goal, like a house or retirement? While high-yield savings accounts are generally best for short to medium-term goals due to their liquidity, understanding your timeline can help you prioritize APY versus other features.
2. Assess Your Comfort with Online Banking
The top high-yield savings accounts are predominantly offered by online banks. If you’re comfortable managing your finances digitally, these options will be perfect. If you prefer the option of visiting a physical branch, you might need to research local credit unions or traditional banks offering competitive online-only accounts, though their APYs might be slightly lower.
3. Review Fee Structures and Minimums
Carefully read the fine print regarding fees. While many high-yield accounts are fee-free, some may have conditions to waive monthly maintenance fees or charge for specific services like wire transfers. Similarly, check for minimum deposit requirements to open the account and any minimum balance requirements to earn the advertised APY.
4. Consider Account Accessibility
How quickly do you need access to your funds? While high-yield savings accounts offer liquidity, electronic transfers to an external checking account can take 1-3 business days. If you need instant access, consider linking your high-yield account to a checking account at the same institution, if available.
5. Read Customer Reviews and Ratings
While APY is crucial, customer experience is equally important. Look for reviews on third-party sites to get a sense of the bank’s customer service, ease of use, and problem resolution efficiency. A high APY is less valuable if you constantly face issues or can’t get timely support.
Maximizing Your Returns: Strategies for High-Yield Savings Accounts
Simply opening a high-yield savings account is the first step. To truly maximize your returns, consider these strategies:
Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account on a regular basis (e.g., weekly, bi-weekly, or monthly). This “set it and forget it” approach ensures consistent growth without requiring constant attention.
Monitor Interest Rate Changes
Interest rates are variable and can change. While the top accounts aim to remain competitive, it’s wise to periodically check if your account is still offering a leading APY. If another bank offers significantly higher rates, consider transferring your funds to optimize your earnings. This doesn’t mean switching every month, but an annual or bi-annual review is a good practice.
Avoid Unnecessary Withdrawals
While these accounts offer liquidity, frequent withdrawals can slow down the power of compound interest. Treat your high-yield savings as a dedicated savings vehicle and resist the temptation to dip into it for non-essential expenses. Some accounts may also have limits on the number of free withdrawals per statement cycle, after which fees might apply.
Link to a High-Yield Checking Account (If Available)
Some online banks offer high-yield checking accounts that complement their savings products. While checking accounts typically have lower APYs, combining them can streamline your banking and potentially unlock additional benefits or higher rates on linked accounts.
Understanding the Fine Print: Important Disclosures
Before committing to any high-yield savings account, it’s crucial to understand the terms and conditions. Here are a few key disclosures to look out for:
Variable APY
Almost all high-yield savings accounts offer a variable APY, meaning the rate can change at any time based on market conditions and the bank’s discretion. While banks generally notify customers of significant changes, always be aware that the rate you sign up for is not guaranteed indefinitely.
Promotional Rates
Some banks may offer an introductory promotional APY that is higher than their standard rate. Be sure to check if the advertised rate is a limited-time offer and what the standard rate will be after the promotional period ends. Our top 3 selections focus on sustainable, competitive rates, but it’s always good to be vigilant.
Monthly Transaction Limits
Regulation D, a federal regulation, used to limit certain types of withdrawals and transfers from savings accounts to six per month. While this regulation was suspended during the pandemic, some banks may still impose their own transaction limits. Always check the bank’s specific policy to avoid unexpected fees or restrictions.
Tax Implications
The interest earned on your high-yield savings accounts is considered taxable income. The bank will typically send you a 1099-INT form if you earn more than a certain amount (usually $10) in interest during the year. Remember to account for this when filing your taxes.
Beyond Savings Accounts: Other High-Yield Options to Consider
While high-yield savings accounts are excellent for liquid funds, it’s worth noting other options for different financial goals:
- Certificates of Deposit (CDs): If you can lock up your money for a specific period (e.g., 6 months to 5 years), CDs often offer even higher fixed interest rates than savings accounts, with the trade-off of less liquidity.
- Money Market Accounts (MMAs): These are a hybrid between checking and savings accounts, often offering competitive interest rates, check-writing privileges, and sometimes a debit card. Their APYs can be similar to high-yield savings accounts.
- Treasury Bills (T-Bills): Short-term government securities that are considered very safe and can offer competitive yields, especially in a high-interest rate environment.
However, for accessible, FDIC-insured savings with excellent returns, high-yield savings accounts remain a top choice.
Conclusion: Secure Your Financial Future with High-Yield Savings
In conclusion, the opportunity to earn over 5.15% APY on your savings is a significant advantage in today’s financial landscape. By choosing one of the top high-yield savings accounts discussed – Account A, Account B, or Account C – you can ensure your money is working as hard as possible for you. These accounts combine high interest rates with the security of FDIC insurance and the convenience of modern online banking, making them indispensable tools for anyone serious about growing their wealth.
Don’t let your money sit idle in a low-interest account. Take the proactive step today to research these options, compare them against your personal financial needs, and make the switch to a high-yield savings account. Your future self (and your growing bank balance) will thank you for it. Remember to regularly review your account’s APY and terms to ensure you’re always getting the best possible return on your savings. Happy saving!
